

Kikoff - Build Credit Quickly
by Kikoff Inc.
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
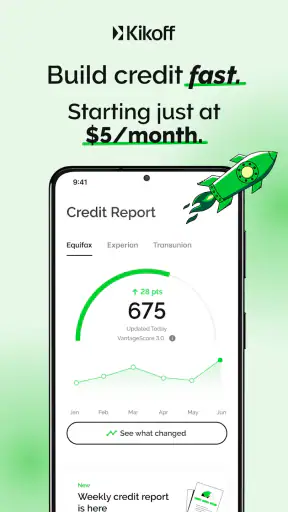
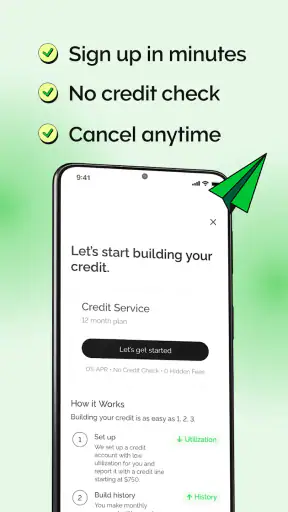
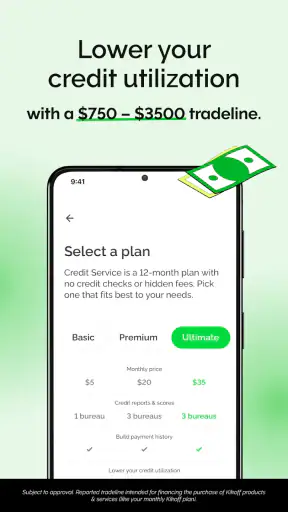
 Analysis by Getfullapps
Credit-building apps often look most appealing on the day you download them, when the promise of a cleaner financial routine feels fresh and easy to understand. My experience with Kikoff - Build Credit Quickly is that its real test comes later: does it still make sense once the initial curiosity disappears? Kikoff is a free finance app from Kikoff Inc., aimed at people who want to work on their credit without beginning with a traditional credit application. Its store summary highlights that no credit check is needed, which immediately makes it more approachable than many conventional credit products.
I see the app as a focused tool rather than a complete personal-finance system. It is not the place I would go for detailed budgeting, investment research, or a full view of every account I own. Its value is narrower and more practical: it gives credit-building a dedicated place in a phone-based routine. That focus can be useful, especially for someone who feels intimidated by banks or has little credit history. It can also become repetitive if you expect constant new features or broad financial guidance.
What using Kikoff feels like beyond the first download
I find that the longer-term experience is shaped less by frequent interaction than by how well the app fits into a calm financial routine. I’ll look at the small choices that can make that routine easier to follow across different reading, movement, and everyday situations, then consider where a focused credit tool may still leave users needing another source of support.
The first week: simple enough to lower the barrier
The strongest first impression is the reduced sense of risk. A traditional credit application can make a new user worry about eligibility, hard inquiries, fees, or choosing the wrong product. Kikoff’s no-credit-check positioning removes one of those immediate concerns and makes the first exploration feel less intimidating. For a person who has been turned down before, or who is simply unsure where to start, that matters more than flashy design.
I also appreciate that the app presents itself as a single-purpose finance tool. Instead of asking me to learn an entire ecosystem, it keeps attention on the credit-building task. That makes it easier to form a basic routine: open the app, review what needs attention, and leave. The experience is most comfortable when I treat it as a small part of financial maintenance rather than as a magic solution.
There is an important distinction between avoiding a credit check and guaranteeing a particular credit outcome. Kikoff makes the starting point feel accessible, but users should still read every in-app explanation carefully and understand what they are agreeing to. Credit reporting is not the same thing as instant score improvement, and a responsible routine usually needs time. I would not install this expecting a dramatic change after a few taps.
The app is free to download, which makes trying it less of a financial commitment than signing up for a conventional paid service. That does not mean every possible financial decision connected with the experience should be made casually. I would still review the terms shown during setup, check how any account activity is described, and avoid treating the app as permission to spend money I do not have.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
A realistic everyday use case
Imagine someone who has recently moved into their first apartment and discovers that a thin credit history makes ordinary applications harder. They may have income and pay bills on time, but little borrowing history to show. In that situation, Kikoff can serve as a deliberately small credit-building routine. The user could check the app on a regular payday, confirm that the account remains in good standing, and then return to normal life instead of constantly searching for another credit product.
The useful habit is not checking the app every hour. It is connecting the review to an existing routine, such as a monthly money check or the day after essential bills are handled. That approach reduces the chance of forgetting the account while also preventing unnecessary anxiety. Credit work is usually more about consistency than excitement, and Kikoff is better suited to that mindset than to someone looking for daily financial entertainment.
Who benefits most from the focused approach
I think Kikoff is most appealing to people who are new to credit, rebuilding after a period of limited access, or looking for a less intimidating first step. It may also suit someone who already understands basic budgeting but wants a separate place to concentrate on credit-related progress. The app’s broad availability is reflected in its strong reception: it has an average rating of 4.8 from roughly 127 thousand ratings, with about 17 thousand written reviews and more than 5 million installs.
Those figures suggest that the app has reached a substantial audience, but popularity should not replace personal judgment. A high rating can tell me that many people find the experience useful; it cannot tell me whether its approach matches my financial situation. I would pay closer attention to the app’s actual workflow and obligations than to the rating alone.
Where it differs from familiar alternatives
The usual alternatives are secured credit cards, starter cards, credit-builder loans, and free credit-monitoring services. A secured card may offer broader everyday usefulness because it can function as a payment method, but it may require a deposit and careful spending discipline. A credit-builder loan follows a different structure and may be more involved than someone wants. A monitoring app can show score changes and alerts, yet it may not provide the same focused path for establishing credit activity.
Kikoff’s advantage is the lower-friction entry point and its narrow purpose. Its trade-off is that it should not be mistaken for a replacement for a well-managed credit card, emergency fund, or budget. If I needed a payment card for travel, recurring bills, or everyday purchases, I would compare Kikoff with a suitable card rather than assuming one tool could cover all those needs.
The first month: turning access into a routine
After the novelty fades, the app’s value depends on whether it gives me a reason to return without demanding too much attention. The most sensible routine is brief and scheduled. I would check for account messages, review any current status, and make sure the activity fits my broader money plan. Then I would close the app. That sounds modest, but modest is exactly what a maintenance-oriented credit tool should be.
A useful tip is to keep a separate personal note about why I started using the service and what I want to improve. I would not rely on memory or on a single score view to judge progress. Instead, I would track broader goals such as qualifying for a future rental, becoming more comfortable with credit, or reducing dependence on applications that feel out of reach. This prevents the app from becoming a source of constant score-checking.
Another practical habit is to review the app alongside a monthly budget rather than in isolation. If the rest of my finances are unstable, credit-building should not push essential expenses into the background. I would first protect rent, food, utilities, and existing obligations. A credit goal is useful only when it supports financial stability instead of competing with it.
What creates lasting value
Kikoff earns recurring value when it helps turn an abstract goal into a repeatable action. Many people know that credit matters but do not know what to do next. A dedicated app can reduce that uncertainty and provide a visible place to return. The benefit is psychological as well as practical: a small, organized routine can feel more manageable than navigating several financial products at once.
Its lasting usefulness also comes from restraint. I do not need a credit-building app to occupy my attention every day. If Kikoff can remain understandable after the initial setup and support a calm monthly check-in, it has a reasonable chance of staying on my phone. In this category, disappearing into the background is not necessarily a weakness. It can mean the tool is doing its job without creating extra noise.
The maintenance burden is low, but not zero
The main responsibility remains with the user. I still need to read notices, understand the account arrangement, keep track of any required actions, and avoid assuming that the app manages my entire financial life. A simple interface can make a process feel effortless, but financial consequences still deserve deliberate attention.
I would also keep my expectations realistic about timing. Building or rebuilding credit is not a one-session task. The app may make the process easier to begin, but it cannot remove the need for patience and consistent behavior. Someone who wants a quick score change may become disappointed, especially if they judge the service after only a short period.
There is a second maintenance issue that is easy to overlook: deciding when the app no longer serves a purpose. If my credit profile becomes stronger and I later choose a different product, I should review the Kikoff account rather than leaving it unattended. Any financial account deserves an intentional decision about whether to keep, change, or close it, based on the terms and my goals at that time.
Where fatigue can set in
The biggest source of fatigue is repetition without visible progress. If I open the app and see essentially the same task month after month, the experience can start to feel like an obligation. That is not unique to Kikoff, but it is especially noticeable in a focused app with a narrow purpose. The more disciplined the user is, the less often they may need to interact with it.
Another possible frustration is the gap between the app’s approachable beginning and the complexity of real credit decisions. Users may still have questions about reporting, timing, account management, and how this fits alongside other accounts. If I needed detailed education, personalized debt planning, or a complete credit overview, I would look for a complementary service rather than expecting Kikoff to answer everything.
I would also skip it if I were tempted to use any credit-building product as a substitute for an emergency fund. Credit can help establish a financial record, but it is not cash savings. Someone already struggling with overdue bills may need a debt counselor, a budget reset, or direct help from creditors before adding another account to monitor.
Questions I would settle before committing
One obvious question is whether the app requires a traditional credit check to get started. Its store summary specifically presents a no-credit-check approach, which is one of its clearest advantages for beginners. Even so, I would distinguish that from approval for every related option or from a promise of a certain credit result. The exact terms shown during the individual signup flow should guide the final decision.
Another question is whether Kikoff replaces a credit card. In my view, no. It is better understood as a focused credit-building option. A card may be more useful for someone who wants payment flexibility and can manage utilization and due dates carefully. Kikoff is more attractive to someone whose priority is beginning a credit routine with less emphasis on everyday purchases.
People also ask whether it is suitable for someone with established credit. It could still be relevant if that person has a specific reason to use its approach, but the benefit may be smaller. I would compare it against existing accounts and goals first. If my credit profile is already healthy, a budget, savings plan, or careful debt payoff strategy might offer more meaningful long-term value.
Finally, I would ask whether the app is appropriate for a young user. It carries an Everyone content rating and has a minimum operating-system requirement of Android 7.0, but age suitability in a financial context is about responsibility as much as app labeling. A younger person should understand the account terms and, where appropriate, discuss the decision with a trusted adult.
Technical and practical fit
Kikoff was released on March 25, 2021, and its current version is 1.177.3016. Those details matter mainly because they help me judge whether the app is maintained and whether my phone can run it. The Android requirement of 7.0 keeps it accessible to many older devices, which is helpful for users who do not replace phones frequently.
I would still keep the app updated through the normal store process and use a secure device lock. Finance apps deserve the same basic care as banking apps, even when their purpose is narrower. I would avoid signing up while distracted, rushing through screens, or ignoring explanations simply because the initial process feels easy.
My long-term verdict
After the first-week appeal wears off, Kikoff remains useful mainly for its focused, approachable entry into credit building. I like that it does not present itself as a complete answer to every money problem and that its no-credit-check positioning can make the first step less stressful. The free price also lowers the barrier to exploring the experience, while the large user base and strong average rating indicate that many people have found it worthwhile.
My reservation is that the app’s value is easy to overestimate. It cannot replace budgeting, savings, careful bill payment, or thoughtful comparison with other credit products. It may also feel too narrow for users who want a full financial dashboard or an everyday spending card. The person who benefits most is willing to accept a quiet, repetitive routine and wait for progress rather than chase instant results.
My recommendation is to treat Kikoff as a small long-term habit, not a shortcut. I would give it space on my phone if I were starting with limited credit, wanted a less intimidating route, and could commit to reviewing the account responsibly. I would skip it if I already had a strong credit strategy, needed broad financial management, or was looking for immediate borrowing power. Once the novelty fades, that honest fit matters more than any initial promise—and for the right beginner, Kikoff can earn its place by staying simple, focused, and easy to revisit.
Pros
- Easy to use with a simple interface.
- Affordable monthly fee for credit building.
- No credit check required to start.
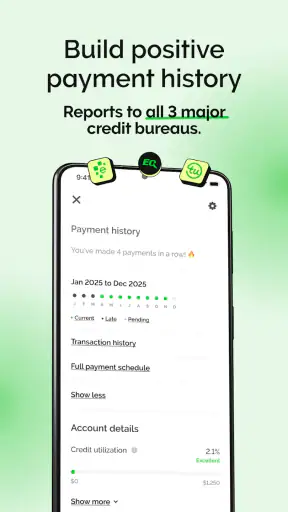
- Reports to major credit bureaus effectively.
- Flexible payment options available.
Cons
- Limited to credit-building activities.
- No traditional credit card features.
- Doesn't offer rewards or cashback.
- Only available in the U.S.
- May take time to see results.
FAQs for Kikoff - Build Credit Quickly
What is Kikoff and how does it help build credit?
Kikoff is a financial app designed to help users build and improve their credit scores. It provides a credit line that reports to major credit bureaus. By making timely payments and managing your credit responsibly, you can incrementally increase your credit score, which is crucial for future financial endeavors.
Is Kikoff safe and secure to use?
Yes, Kikoff prioritizes user security and data protection. It employs industry-standard encryption and security measures to ensure your personal and financial information is safe. Additionally, Kikoff is compliant with relevant financial regulations, providing users with peace of mind while using the app.
How much does it cost to use Kikoff?
Kikoff offers a very affordable plan, typically charging a minimal monthly fee. This fee grants access to its credit-building services, including the credit line and educational resources. The low cost is designed to make credit building accessible to everyone, without any hidden fees or charges.
How quickly can I expect to see improvements in my credit score with Kikoff?
While individual results may vary, many users report seeing improvements in their credit scores within a few months of consistent use. It’s essential to make timely payments and follow Kikoff’s guidance to achieve optimal results. Patience and consistency are key to effectively building your credit.
Can Kikoff be used alongside other credit-building tools or apps?
Yes, Kikoff can be utilized in conjunction with other credit-building tools and apps. It often complements other financial strategies by providing a structured and disciplined approach to credit improvement. However, users should ensure they are managing all tools responsibly to avoid financial missteps.

Kikoff - Build Credit Quickly
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via hello@kikoff.com, visit https://kikoff.com, or review their https://kikoff.com/privacy-policy.html.










